AI data center capacity is becoming a weapon in the chip war, and AMD’s deal with Core Scientific shows why. The company is not just chasing Nvidia with accelerators; it is trying to help customers find the power-heavy infrastructure needed to run those chips at scale.
That shift matters because the AI race is moving beyond silicon specifications. The next constraint sits closer to AI infrastructure buildout: power, land, cooling, racks, and deployable capacity that can turn chips into live workloads.
AI Data Center Capacity Now Sells the Chip
AMD signed a partnership with Core Scientific that gives the chipmaker access to more than 500 megawatts of U.S. infrastructure starting in 2027, with the ability to expand up to 2.5 gigawatts. The companies said the arrangement will support end-customer deployments of AMD AI solutions, including Instinct GPUs, EPYC CPUs, and ROCm software through the infrastructure partnership terms.
That is a bigger statement than a normal supply deal. It suggests AMD understands that customers do not only need accelerator availability. They need a physical path to deployment.
For years, Nvidia’s lead has rested on chips, software, networking, and developer confidence. AMD has been pushing back through its Instinct portfolio and ROCm stack. But performance claims alone are not enough when large buyers are fighting for power and data center space.
AMD’s new strategy is closer to infrastructure packaging. It wants to tell customers: here is the hardware, here is the software, and here is a route to capacity.
That makes capacity part of sales.
Why Core Scientific Is Suddenly Useful to AI
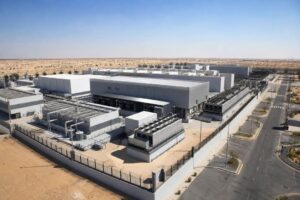
Core Scientific built its business around high-density computing for Bitcoin mining. That market required large power access, industrial facilities, uptime discipline, and the ability to operate compute at scale.
AI workloads are different, but the physical foundation overlaps. A Bitcoin mining site is not automatically an AI data center, yet it may have valuable pieces already in place: electrical capacity, land, utility relationships, and high-load operating experience.
The shift is visible across the company’s positioning. Core Scientific has been moving deeper into high-performance computing and AI hosting, with prior arrangements tied to CoreWeave and now a much larger AMD-linked opportunity.
Reuters described the agreement as giving AMD access to up to 2.5 gigawatts of data center capacity, beginning with more than 500 megawatts in 2027 through a wider capacity agreement.
The interesting part is not that a miner found a hotter market. It is that crypto-era infrastructure may be repurposed into the next AI landlord layer.
The Crypto-to-AI Pivot Has Real Limits
The conversion story should not be oversold. AI data centers need stronger networking, tighter reliability, enterprise-grade service levels, more complex cooling, hardware integration, and a different customer profile than Bitcoin mining.
Mining can tolerate some economics and uptime patterns that AI customers may reject. A training cluster or inference service has different latency, security, and operational expectations. GPU deployments can also require high-bandwidth interconnects, advanced rack design, and more demanding thermal management.
That is why the partnership includes collaboration on physical infrastructure design, not merely space rental. AMD needs the sites to be suitable for its technology roadmap, not just powered buildings with compute density.
The decision factors are different from crypto mining.
| Decision Factor | Mining Infrastructure Advantage | AI Deployment Requirement |
|---|---|---|
| Power access | Large-load sites already exist | Reliable delivery for dense AI clusters |
| Facility experience | Operators understand continuous compute | Enterprise-grade uptime and security |
| Speed to market | Existing sites can shorten timelines | Retrofit complexity can slow readiness |
| Hardware model | Mining uses simpler specialized equipment | AI needs GPUs, CPUs, networking, and software |
| Revenue quality | Mining follows crypto economics | AI depends on contracted customer demand |
The table shows why Core Scientific is valuable but not risk-free. It offers a head start, not a finished AI cloud.
AMD Is Building Around Nvidia’s Biggest Advantage
AMD has strong silicon, but Nvidia’s advantage is ecosystem depth. Customers know the software, the libraries, the deployment patterns, and the procurement path. For AMD to gain share, it must reduce friction at every layer.
That is where infrastructure partnerships matter. If AMD can combine Instinct hardware, EPYC processors, ROCm software, and access to high-density data center capacity, it can present a more complete alternative.
AMD’s Instinct MI350 series is positioned for generative AI and high-performance computing, with the company emphasizing memory capacity, bandwidth, and ROCm support through its AI accelerator platform. But the hardware still needs to be installed, powered, cooled, and operated.
This is why the Core Scientific deal is strategically useful. It helps AMD compete where customer hesitation often appears: not “Can the chip run?” but “Can we deploy enough of it soon enough?”
That is infrastructure-assisted competition.
The Financial Structure Reveals the Stakes
The deal also includes market-priced warrants that give AMD the right to purchase Core Scientific stock under certain commercial conditions. That creates a financial alignment between chip deployment and infrastructure success.
Core Scientific’s second-quarter materials said the AMD partnership is anchored by 15-year agreements covering roughly 530 megawatts across five sites and more than $14 billion of potential base contracted revenue through its latest high-density colocation update.
That long-term structure matters. AI infrastructure is not being built for short experimental bursts. Companies are signing multi-year commitments because the physical buildout requires confidence that demand will last.
For Core Scientific, the opportunity is a more stable revenue model than pure mining exposure. For AMD, the opportunity is a channel that can help customers deploy hardware faster and at scale.
The risk is that both sides must execute across construction, power, cooling, software, customer demand, and financing.
The Next Signal Is Utilization
The first signal to watch is whether customers actually take the capacity. Announced megawatts matter, but revenue depends on filled racks and operational workloads.
The second signal is whether the 2027 capacity arrives on schedule. AI infrastructure delays are common because power delivery, equipment supply, and construction are difficult to synchronize.
The third signal is whether other crypto infrastructure companies follow Core Scientific’s path. If they do, the Bitcoin mining boom may become a strange but important feeder system for AI.
The fourth signal is ROCm adoption. Infrastructure access can open the door, but customers need software confidence before large deployments feel safe.
That connects back to Nvidia Blackwell infrastructure, where the hardware ecosystem is as important as the chip itself.
Bitcoin Miners May Become AI’s Fastest Landlords
AI data center capacity is now one of the hardest assets to secure in the entire technology stack. AMD’s Core Scientific deal shows that chip companies are no longer competing only inside the server. They are competing for the places those servers can live.
Bitcoin miners spent years building and operating power-heavy computing sites. AI has made some of those assets valuable in a new way. The companies that can convert them into reliable, high-density AI infrastructure may become unexpected winners in the next buildout.
For AMD, this is a practical move against Nvidia’s ecosystem advantage. If customers can get chips, software, and capacity together, AMD has a cleaner path into large deployments. The AI race is still about accelerators, but the next decisive advantage may belong to whoever can make those accelerators deployable fastest.